
The Mirror of Excess: What Luxury Goods Reveal About a Changing Economy
This article explores the relationship between luxury goods and the economy within the span of the last six years.
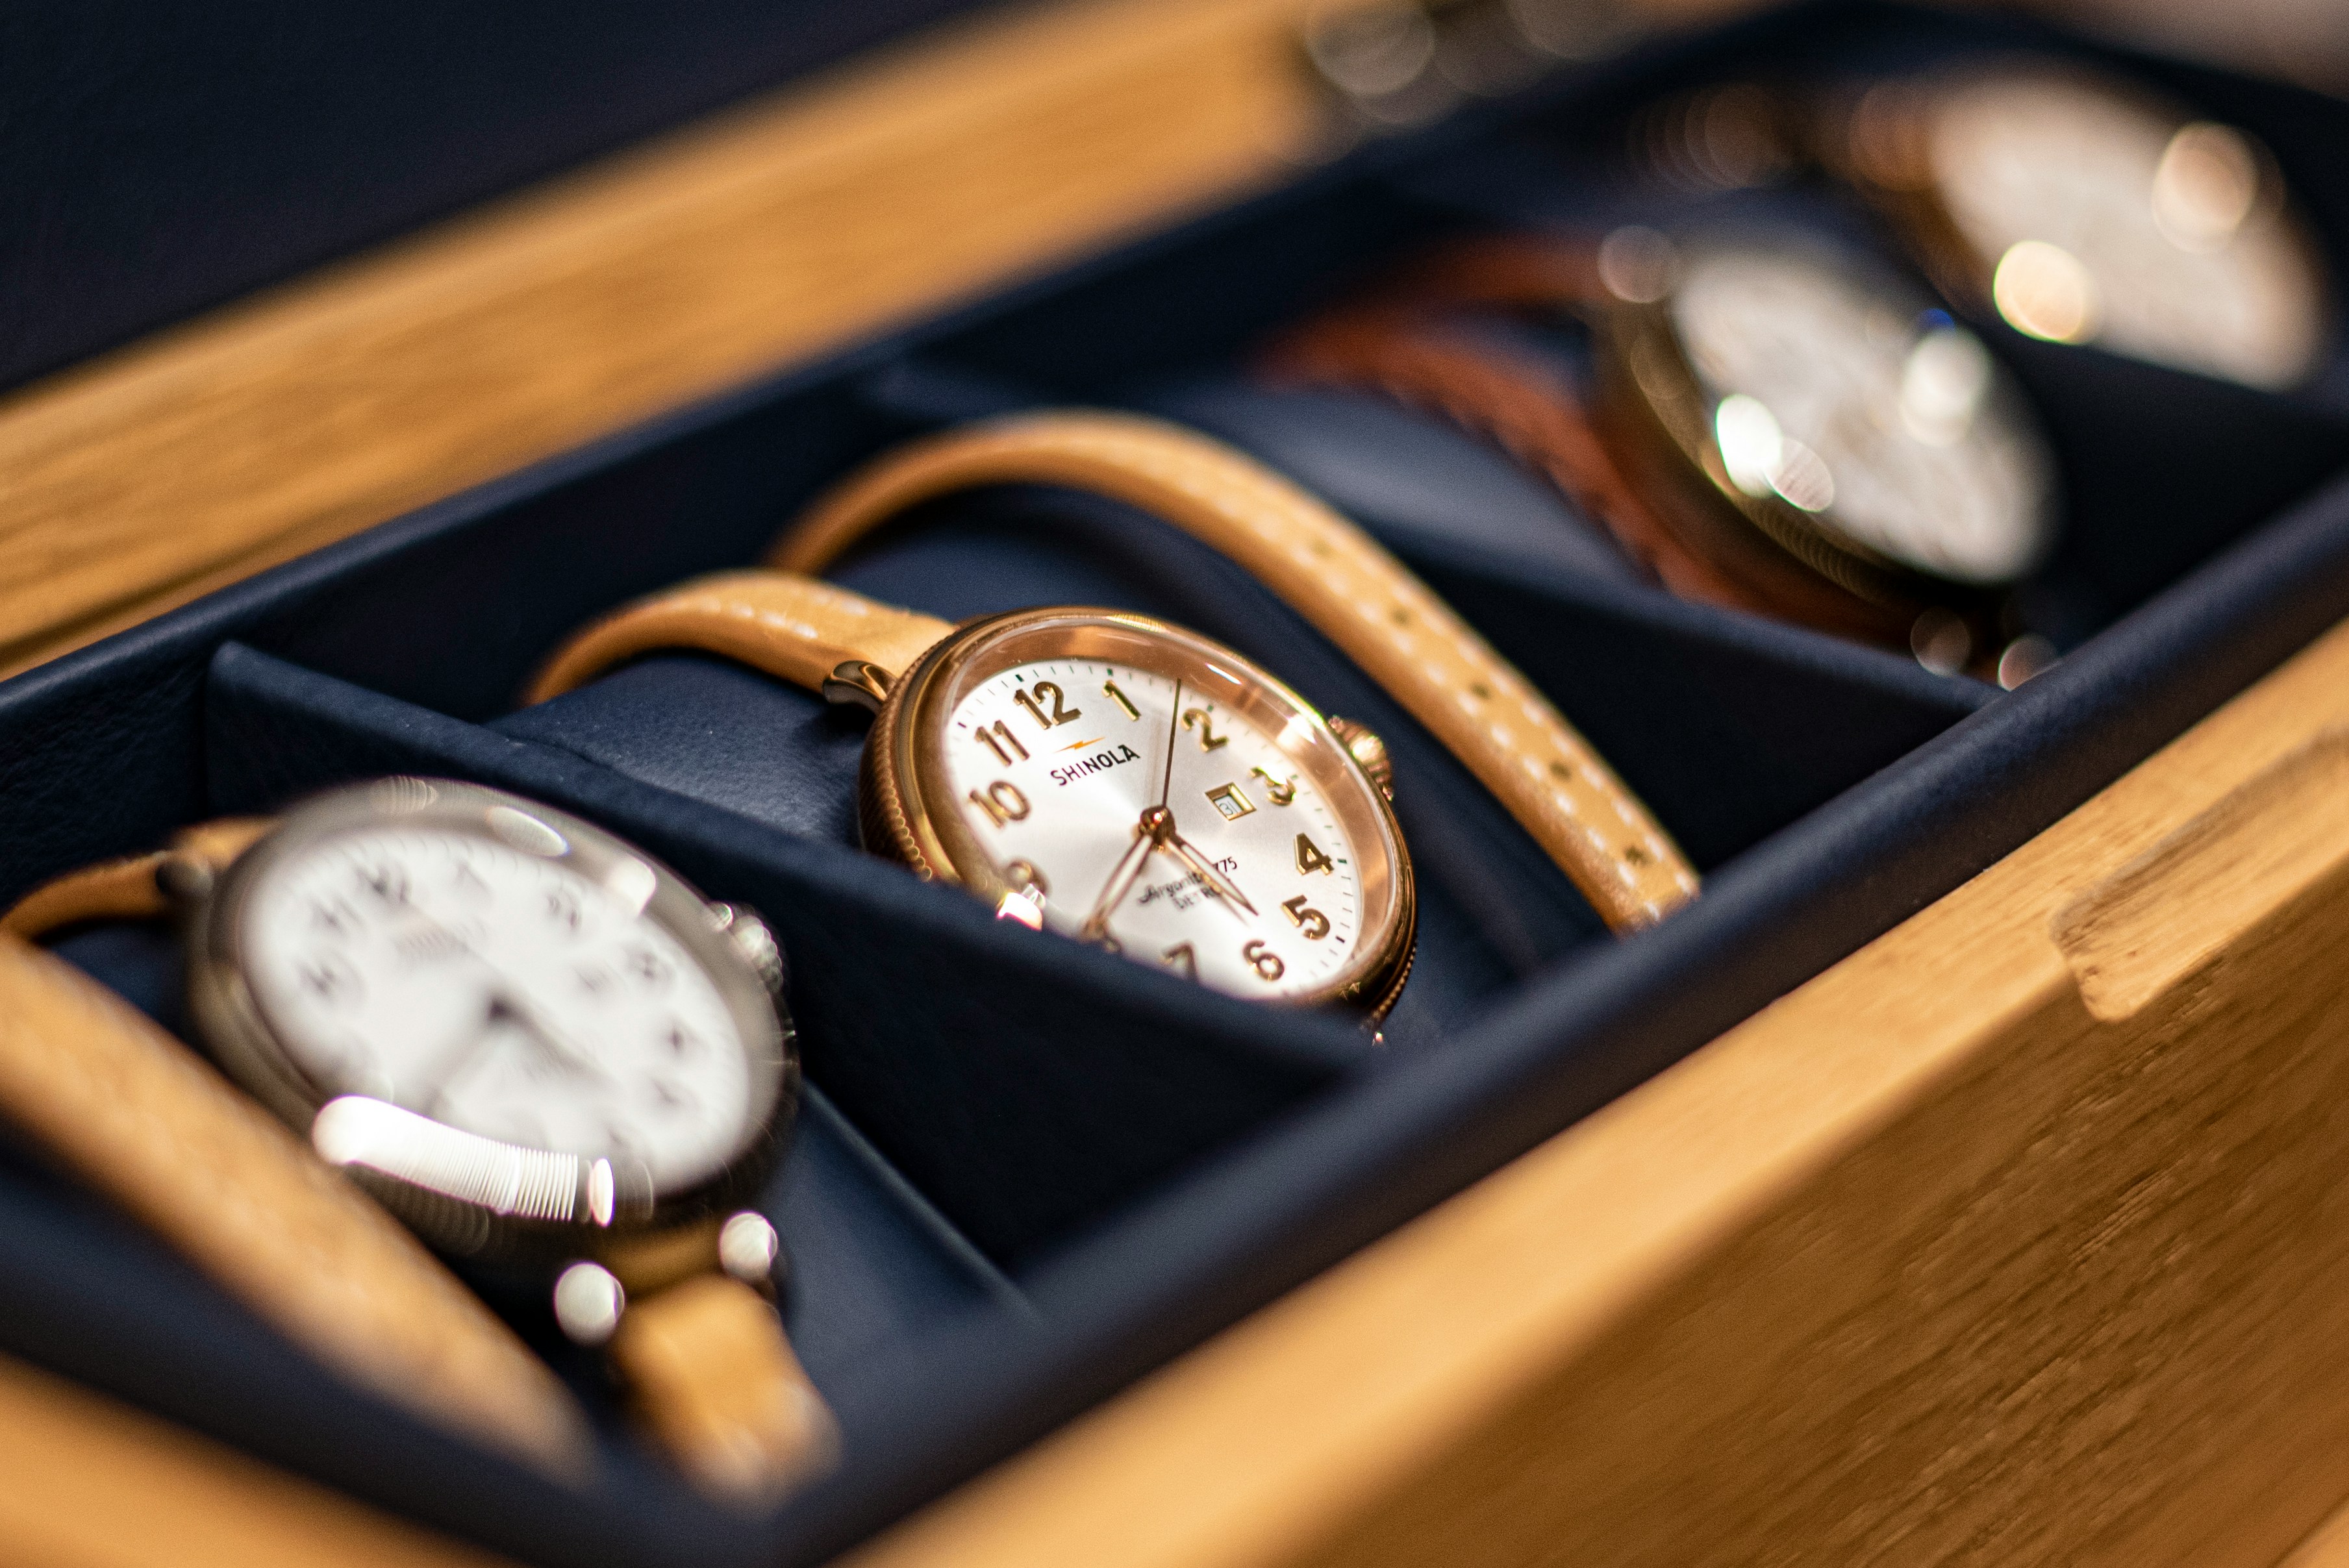
In 1899, Thorstein Veblen observed that the desirability of certain goods tended to increase with increases in price, since their utility resided in their capacity to demonstrate wealth.1 A handbag that sold for the price of a used car could not be purchased for the utility of carrying keys. Since luxury spending was discretionary and depended on confidence, it was an unusually accurate barometer of the overall economic conditions. In the span of the last six years, the luxury market experienced a boom and then a stagnation that eventually led to a fragile, uneven recovery, a pattern encompassing many of the most salient economic trends of the present day: the aftershocks of stimulus, the re-emergence of inflation, the widening of the gap between the very rich and the rest of us, and a subtle shift in valuation.
The boom came first: when restrictions were lifted, consumers in rich countries emerged with their savings from stimulus checks and cancelled vacations, and rising asset prices were enabled by near-zero percent interest rates. Luxury houses announced double-digit growth year on year while raising prices repeatedly without losing a customer. At the time, the trend was considered business as usual, but analysts have since noted that it was a post-Covid anomaly that will be hard to rival.2 The boom was driven by the same forces that drove housing and stocks in the same interval: cheap money and pent-up demand.
Then the money got more expensive: central banks began to raise interest rates in an effort to fight inflation, reversing the conditions that had contributed to luxury sales. Middle- class households, faced with soaring grocery, rent and loan bills, began to cut back on discretionary spending. The numbers tell the tale: personal luxury goods sales fell from €364 billion in 2024 to a forecast €358 billion in 2025, a modest decline that, after currency adjustments, was flat.3 More salient, the market lost about 20 million consumers in 2025, leaving around 330 million active buyers, or a 15% decline from 2022, bringing the customer base back to 2013 levels.4
The market contraction is indicative of perhaps the most important economic trend that luxury typifies: the "K-shaped" economy, the fortunes of the wealthy and everyone else diverging. Ultra-rich buyers sustained demand for high-end goods while aspirational consumers tapered their expenditures.5 The concentration is remarkable: top 0.1% clients account for 37% of the value of luxury, with each spending around €360,000 a year on personal luxury goods.6 Brands that were focused on the very top thrived, while those that had relied on middle-class shoppers with occasional splurges struggled. Hermès—known for its scarcity and niche appeal—ended 2025 with sales above €16 billion and a 41% operating margin.7 Gucci—which had previously relied on its wider appeal to grow—posted a 19% decline in sales in 2025.8 The chasm in fortunes between these two houses, however small, represents the chasm between asset owners (whose value had risen on the stock market) and wage-earners (whose wages were eroded by inflation).
Luxury pricing also indicates ways companies responded to the inflation and trade tensions. During the boom period, brands were raising prices at a faster rate than inflation was, testing consumer tolerance. When the U.S. imposed new tariffs in 2025, Hermès announced that it would fully offset the impact by raising selling prices,9 a move that only a company with immense pricing power could make. For many other brands, however, repeated increases that failed to deliver commensurate improvement in perceived value made consumers wary of further price hikes: a microcosm of the broad post-inflation attitude of value consciousness.
Geography provides a telling economic narrative. For more than a decade, Chinese shoppers have been the engine of luxury growth, reflective of China's quick rise of middle-class wealth. But as China's property market collapsed and the country's economy slowed, this engine began to sputter. Bain noted that the economic slowdown in Mainland China remained challenging in 2025, with some improvement.10 Meanwhile, the U.S. turned out to be the bright spot: first-half 2026 growth was driven largely by strong American demand fuelled by robust financial markets and continued wealth creation among affluent consumers.11 Luxury sales, in other words, track where wealth is being created and, in recent years, that has meant rising stock portfolios in America rather than rising wages in Asia.
Finally, luxury highlights a shifting attitude to how people wish to spend money at all. Across wealthy societies, consumers are shifting from preference for objects to experiences. Bain describes a "tectonic shift" to luxury experiences such as hospitality, cruises, fine dining, and away from traditional luxury goods.12 Categories such as hospitality, fine dining, wellness, and travel, in fact, have driven all net market growth since 2023.13 Luxury companies have responded accordingly, with LVMH partnering with Formula 1 to offer a $13,450 trackside dining experience for a handful of guests.14 In tandem, the resale market has absorbed much of the demand that has been squeezed out of boutiques as priced-out shoppers gravitate towards authentic secondhand goods,15 suggesting that the desire for status has not disappeared so much as found cheaper channels.
By mid-2026, the industry had shown signs of stabilizing, with LVMH's fashion and leather goods division reporting its first organic sales increase after seven consecutive quarters of decline.16 But this recovery looks nothing like the boom. It is more concentrated on the very rich and focused on experiences rather than objects. The market for the world's most expensive handbags and watches is a small slice of the global economy, but it condenses the largest forces into a readable story: easy money giving way to expensive money, prosperity concentrating at the top, and a growing sense that what people value is not as easily put in a shopping bag.
Notes
- Veblen, Thorstein. The Theory of the Leisure Class. Macmillan, 1899. ↩
- "LVMH Group Q2 2026 Earnings: Fashion Unit Sees First Sales Rise in Two Years." WWD, 27 July 2026, wwd.com/business-news/financial/lvmh-fashion-leather-goods-q2-2026-increase-1239083331/. Accessed 27 Sept. 2026. ↩
- "Luxury Is Ready for a New Era After Stabilizing in 2025." Bain & Company, 20 Nov. 2025, www.bain.com/insights/luxury-is-ready-for-a-new-era-after-stabilizing-in-2025-snap-chart/. Accessed 27 Sept. 2026. ↩
- "Bain: Global Luxury Client Base Shrinks to 330M in 2025." Mission Media, 11 Mar. 2026, missionmedia.asia/luxury-market-trends-asia-2025-bain-report/. Accessed 27 Sept. 2026. ↩
- Bain & Company. "Global Luxury Stays Resilient Despite Economic Headwinds and Shifting Consumer Trends That Reshape Market—Bain & Company and Altagamma." Bain & Company, Nov. 2025, www.bain.com/about/media-center/press-releases/20252/global-luxury-stays-resilient-despite-economic-headwinds-and-shifting-consumer-trends-that-reshape-marketbain--company-and-altagamma/. Accessed 27 Sept. 2026. ↩
- "Bain: Global Luxury Client Base Shrinks to 330M in 2025." Mission Media, 11 Mar. 2026, missionmedia.asia/luxury-market-trends-asia-2025-bain-report/. Accessed 27 Sept. 2026. ↩
- "Fashion Outlook 2026: Spotlight on the Leading Luxury Conglomerates." Modaes Global, 24 June 2026, www.modaes.com/global/companies/the-2026-fashion-map-the-ten-largest-luxury-groups. Accessed 27 Sept. 2026. ↩
- "LVMH, Hermès H1 2026 Revenue Growth Signals Luxury Rebound." Asia Beauty Brief, 13 Aug. 2026, asiabeautybrief.com/article/luxury-market-rebounds-h1-2026-lvmh-hermes-report-growth-china-recovery. Accessed 27 Sept. 2026. ↩
- "Hermes to 'Fully Offset' Tariff Impacts, Q1 Sales Growth Disappoints." Sharecast News, 17 Apr. 2025. Hargreaves Lansdown, www.hl.co.uk/shares/shares-search-results/h/hermes-international-npv/share-news. Accessed 27 Sept. 2026. ↩
- "Luxury Is Ready for a New Era After Stabilizing in 2025." Bain & Company, 20 Nov. 2025, www.bain.com/insights/luxury-is-ready-for-a-new-era-after-stabilizing-in-2025-snap-chart/. Accessed 27 Sept. 2026. ↩
- "LVMH, Hermès H1 2026 Revenue Growth Signals Luxury Rebound." Asia Beauty Brief, 13 Aug. 2026, asiabeautybrief.com/article/luxury-market-rebounds-h1-2026-lvmh-hermes-report-growth-china-recovery. Accessed 27 Sept. 2026. ↩
- Bain & Company. "Global Luxury Stays Resilient Despite Economic Headwinds and Shifting Consumer Trends That Reshape Market—Bain & Company and Altagamma." Bain & Company, Nov. 2025, www.bain.com/about/media-center/press-releases/20252/global-luxury-stays-resilient-despite-economic-headwinds-and-shifting-consumer-trends-that-reshape-marketbain--company-and-altagamma/. Accessed 27 Sept. 2026. ↩
- "Global Luxury Market 2025: Key Insights from Bain Industry Report." World Luxury Chamber, 12 Jan. 2026, worldluxurychamber.com/global-luxury-market-2025-bain-report-summary/. Accessed 27 Sept. 2026. ↩
- "LVMH Group Q2 2026 Earnings: Fashion Unit Sees First Sales Rise in Two Years." WWD, 27 July 2026, wwd.com/business-news/financial/lvmh-fashion-leather-goods-q2-2026-increase-1239083331/. Accessed 27 Sept. 2026. ↩
- "LVMH Q2 2026 Results & What They Mean for Luxury Resale." SAIKA, 27 July 2026, www.saikacollective.com/blogs/saika-luxury-authentication-journal/luxurys-two-tier-market-just-got-its-receipt-what-lvmhs-q2-2026-results-mean-for-resale. Accessed 27 Sept. 2026. ↩
- "LVMH Group Q2 2026 Earnings: Fashion Unit Sees First Sales Rise in Two Years." WWD, 27 July 2026, wwd.com/business-news/financial/lvmh-fashion-leather-goods-q2-2026-increase-1239083331/. Accessed 27 Sept. 2026. ↩
Enjoyed this article?
Subscribe to get the latest economic analysis delivered to your inbox.
Comments
Related Articles
The Price of Progress: Inside China's Semiconductor Industry
This article summarizes three interviews the writer conducted with industry professionals in China on the topics of Competition,...
The Economics of Exclusivity
A pair of sneakers costing the manufacturer $100 may sell for $4,000 nowadays. In today’s drop culture, brands are turning scarcity into...
The Advantages of Photonic Technologies: A Step Closer to Sustainability Within AI Data Centers
AI data centers are driving a surge in Photonics as demand for faster, more energy-efficient technology grows.